Five cities buck global super-prime slowdown
3. 12. 2023
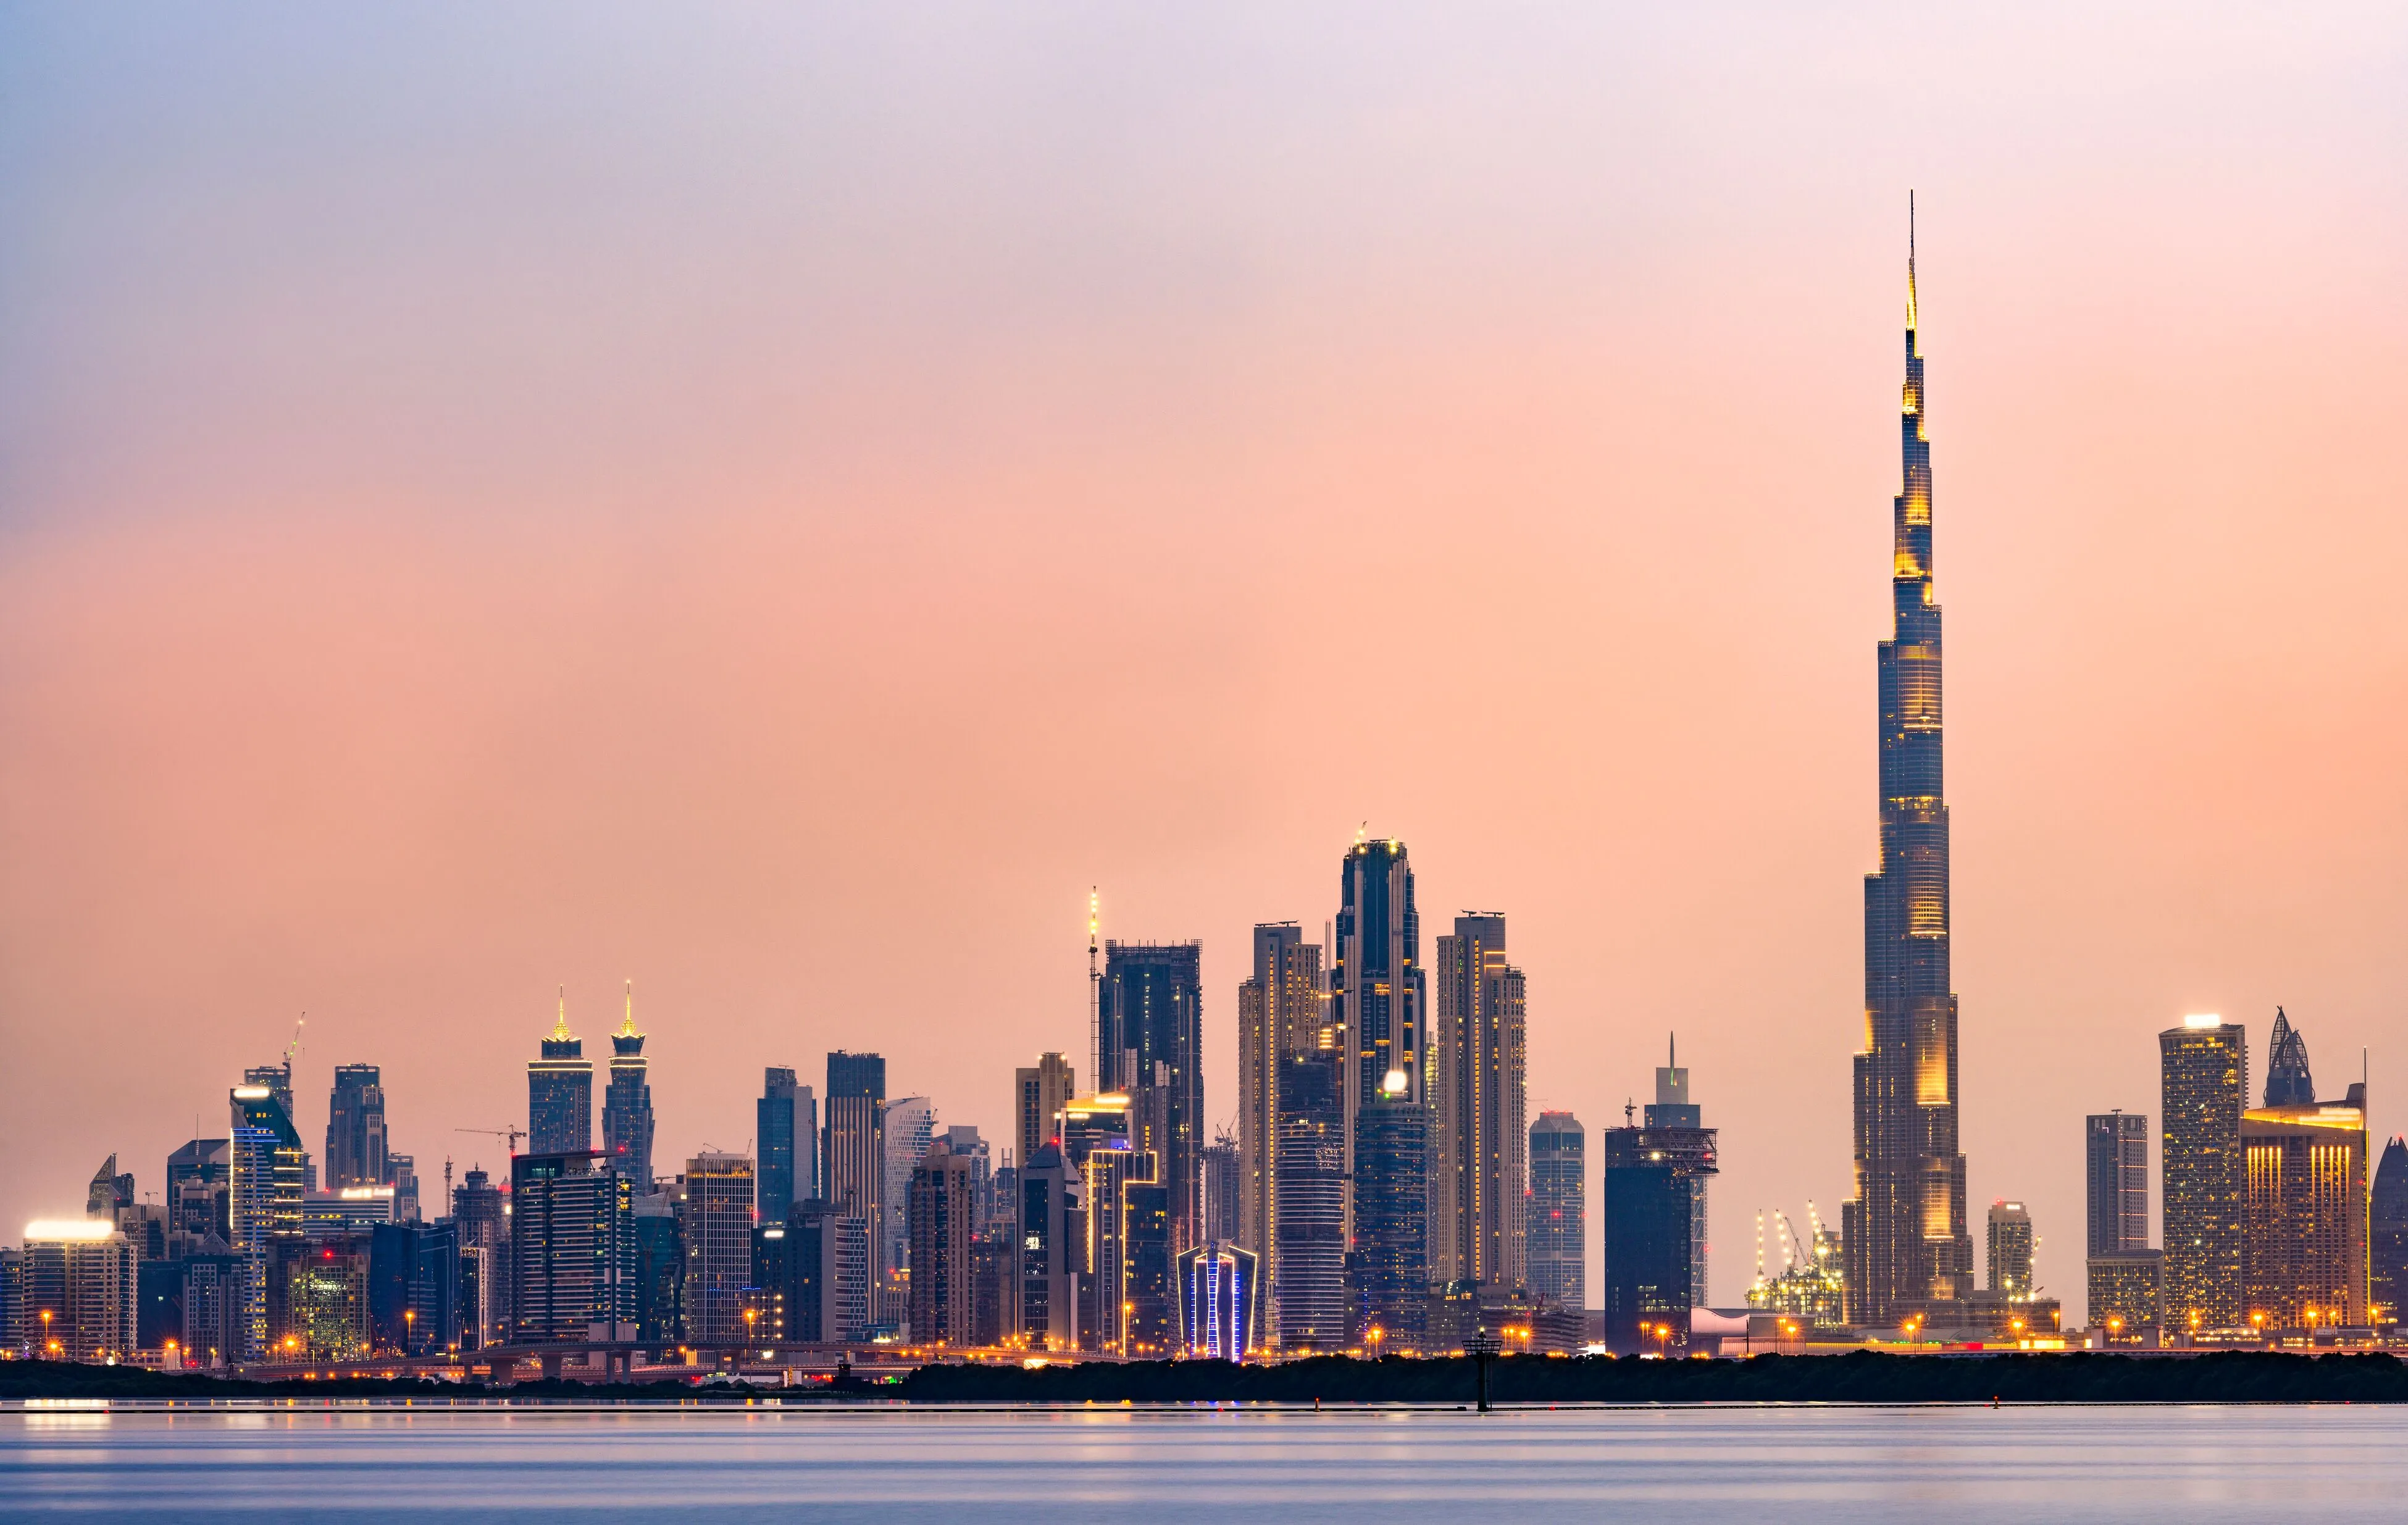
Below are the key highlights of the Global Super-Prime Intelligence report. Download the full report for all the details.
Key highlights:
Global super-prime ($10m+) residential sales fell 2.4% in Q3 2023 on a year-on-year basis, with 362 sales across the 12 markets covered in the three months to September compared to 371 in the same period last year.
Five markets saw volumes rise through the last quarter on a year-on-year basis, with Hong Kong, Dubai, Geneva, Miami and Sydney seeing more sales in Q3 this year against Q3 2022
Dubai once again leads the ranking of quarterly sales, a position it has held since Q4 2022. London follows in second position, with Hong Kong sitting in third place.
The super-prime market is driven more than most by new-build completions. Strong sales volumes in 2021 were flattered to an extent by delayed completions in 2020. As we move into 2024, the tailwind from new build sales will weaken as the lower volume of new project starts through the pandemic begins to be felt.

Other tips
10/2026
Czech Investment Market in Q3 2026
Czech real estate investment exceeded €720 million in Q3 2026, up 92% year-on-year. Domestic investors accounted for 90% of activity.
09/2026
Czech Capital Drives Investment Activity Across Central and Eastern Europe
Commercial property investments in CEE surpassed €5.5 billion in H1 2026. Czech capital accounted for more than one-third of all investment activity across the region.
07/2026
Czech Investment Market Q2 2026
We expect investor demand to remain strong throughout the second half of the year. The market is currently seeing a number of transactions under negotiation, including prime office buildings in Prague...